Last updated October 13, 2026
There isn’t really one “first-time home buyer loan.”
If you’re buying your first house in St. Louis, you may actually be choosing between several different ways to finance the same property: Conventional, FHA, VA if you’re eligible, or USDA if both you and the property qualify.
Then there is a second decision: whether you qualify for a first-time-buyer or down-payment-assistance program that can work with that financing.
Those aren’t necessarily the same decision.
And the mortgage you choose can change more than how much you put down.
It can change how much you borrow, whether you pay mortgage insurance, whether an upfront program fee gets added to your loan, how much cash you keep after closing, and sometimes which properties are practical to pursue.
So instead of starting with four definitions, let’s start with one house.
What happens if four buyers purchase the same $300,000 St. Louis home using four different loans?
If you're trying to understand where financing fits into everything else, start with my complete guide to buying a home in St. Louis, which walks through the process from preparing your finances through closing.
Before choosing a loan, get pre-approved to understand your real options. How to Get Pre-Approved for a Mortgage in St. Louis → →Loan rules from HUD, VA, USDA, Fannie Mae and the CFPB; 2026 limits from HUD and FHFA. See sources ↓
There isn’t one. The smallest down payment doesn’t always produce the smallest payment, and the smallest payment doesn’t always make a loan the right one. Compare what each loan does to your cash, your loan balance, your monthly payment and the houses you can buy. Try the calculator ↓
Conventional can go as low as 3% down in some cases, with private mortgage insurance you can usually cancel later. FHA needs 3.5% down and charges upfront and annual mortgage insurance. VA needs no down payment for eligible veterans and has no monthly mortgage insurance, but most borrowers pay a one-time funding fee. USDA needs no down payment, but the household and the property both have to qualify.
No. A 0% down loan removes the down payment, not the other costs of buying. 0% Down Isn’t $0 to Close ↓
The 2026 FHA limit for a one-unit home in St. Louis County and the City is $541,287, HUD’s floor amount for most of Missouri. The 2026 conforming limit for conventional loans is $832,750 for a one-unit home. Confirm the exact figure for your county with your lender or HUD’s lookup tool.
Not automatically. A seller is choosing the offer they believe will close, and financing is one factor alongside price, buyer qualification, appraisal risk and the rest of the terms. Loan Type and Offer Strength ↓
Four different payments, even at the same price and the same rate. A mortgage comparison gets confusing quickly because lenders quote different rates, buyers put different amounts down, taxes vary by property, and mortgage insurance depends on the borrower.
So the calculator below lets you control those variables yourself.
Start by holding the house and interest rate constant.
That answers a much cleaner question:
If the house costs exactly the same and the interest rate is exactly the same, what does the loan structure itself change?
You’ll see the down payment, starting loan balance, principal and interest, mortgage or program insurance, and estimated monthly housing payment for each option.
Then change the assumptions.
That is where the comparison becomes useful to you rather than just another mortgage chart on the internet.
Every number below is an estimate. Set the shared assumptions, then change the down payment on each loan. Down payment is a choice with consequences, not only a minimum.
Calculator methodology: This tool provides illustrative estimates for comparing financing structures. It is not a Loan Estimate, lending quote, preapproval or determination of eligibility. Interest rates, PMI, taxes, homeowners insurance, closing costs and lender requirements vary. FHA, VA and USDA program rules can change. Verify your actual financing terms with a qualified lender before making a purchase decision.
How the estimates work: principal and interest use standard fixed-rate amortization on each loan’s starting balance, including any financed program fee. Conventional PMI is the estimated annual rate × the loan amount ÷ 12 and is removed at 20% down or more. FHA annual MIP and the USDA annual fee are first-year estimates, applied to the average scheduled balance during year one (the FHA base loan, and the full USDA loan). FHA down payments below the 3.5% minimum investment are not modeled; USDA is shown at 0% down only. The tool does not check FHA loan limits, conforming loan limits or any program eligibility. “Initial down payment” is not cash to close.
Because the price of the house is only one part of the payment.
Your down payment changes how much you borrow.
FHA can add an upfront mortgage insurance premium to the starting loan balance and then charge annual mortgage insurance.
VA can finance a funding fee into the mortgage for borrowers who aren’t exempt, but VA does not require monthly mortgage insurance.
USDA can finance its upfront guarantee fee and also charges an annual fee.
Conventional financing doesn’t have a government program fee structured the same way, but a buyer putting less than 20% down will commonly encounter private mortgage insurance. Unlike a government-set program fee, the actual cost of PMI varies.
And then there is the interest rate.
We held the rate equal in the first comparison intentionally. In the real world, FHA, VA, USDA and Conventional rates do not have to be identical.
That’s why the calculator lets you change the assumptions instead of pretending one example is a mortgage quote.
No. A 0% down loan removes the down payment, not the other costs of buying.
The down payment is only one piece of the money involved in purchasing a home.
Depending on the transaction, a buyer may also have lender charges, title and settlement costs, prepaid homeowners insurance, tax and insurance escrow deposits, appraisal and inspection expenses, and other costs.
Credits from a seller, lender or assistance program can also change what the buyer ultimately brings to closing.
That’s why the calculator above shows initial down payment, not “cash to close.”
Your actual cash-to-close figure comes from the specific transaction and eventually appears on your Closing Disclosure.
Beyond down payment and mortgage insurance, understand all the costs due at closing. Buyer Closing Costs in St. Louis → →Usually not. On many conventional loans you can ask to cancel private mortgage insurance once your balance is scheduled to reach 80% of the home’s original value, and it ends automatically at 78% if you’re current. And you don’t need 20% down to use conventional financing (how much down each loan needs).
Certain Conventional purchase transactions can reach 97% loan-to-value, meaning a qualifying buyer may put as little as 3% down.
That doesn’t mean every buyer qualifies for every low-down-payment Conventional product.
And putting less than 20% down commonly means paying private mortgage insurance.
The important distinction is that PMI is not necessarily permanent.
For many mortgages covered by federal PMI-cancellation rules, a borrower can request cancellation when the principal balance is scheduled to reach 80% of the home’s original value, provided the applicable requirements are met. In general, automatic termination occurs when the scheduled balance reaches 78% if the borrower is current.
That makes Conventional worth comparing even when FHA initially looks easier or requires a similar amount of cash.
Because of mortgage insurance: a 1.75% upfront premium added to the loan, plus an annual premium for as long as the rules require. FHA requires a minimum investment of 3.5% of the property’s adjusted value for the standard maximum-financing scenario.
But that isn’t the whole FHA calculation.
Most FHA purchase loans also carry a 1.75% upfront mortgage insurance premium. That premium can be financed into the mortgage, which means the buyer doesn’t necessarily write a check for it at closing—but financing it increases the amount being borrowed.
Then there is annual mortgage insurance.
For the standard 30-year, minimum-down-payment example used in our calculator, the current annual MIP rate is 0.55%.
That’s why comparing FHA to Conventional solely by looking at the down payment can be misleading.
FHA may be an excellent financing option for a buyer whose financial profile fits the program. But the useful question isn’t:
Which loan asks me for the smallest percentage down?
It’s:
What does each loan do to my cash, my starting balance and my monthly payment?
FHA is also not exclusively a first-time-homebuyer loan.
Not by building equity. With less than 10% down, FHA’s annual premium lasts the life of the loan; with 10% or more down, it lasts 11 years. The usual way out early is refinancing into a conventional loan once you have 20% equity.
It should weigh heavily, because your credit score matters more with conventional loans than FHA loans. For the minimum scores themselves, see what credit score you need.
FHA mortgage insurance rates are relatively fixed regardless of credit score -- a 580 score and a 720 score pay nearly the same MIP rate. Conventional PMI rates are heavily influenced by credit score. A 760 credit score might pay 0.3% PMI while a 640 score pays 1.5% PMI on the same loan.
This means:
Usually a one-time funding fee instead of monthly mortgage insurance. If you’re eligible for the VA home-loan benefit, VA deserves a real comparison, not a footnote underneath FHA and conventional.
VA does not require a down payment when the purchase price does not exceed the property’s appraised value, although individual circumstances, lender requirements or entitlement considerations can change the transaction.
VA also does not require monthly private mortgage insurance or FHA-style mortgage insurance.
Instead, many VA borrowers pay a one-time funding fee.
For a first use with less than 5% down, the current funding fee is 2.15% of the loan amount. For a subsequent use at less than 5% down, it is 3.30%.
Some borrowers are exempt from the funding fee entirely.
That creates an interesting comparison.
A VA buyer may start with a slightly larger financed balance because of the funding fee while still avoiding the monthly mortgage-insurance charge found in other low-down-payment structures.
And an exempt VA borrower changes the comparison again.
That’s exactly why the calculator lets you switch between first use, subsequent use and funding-fee exempt.
If you're eligible for VA financing, the loan comparison is only part of the process. My St. Louis VA home-buying guidance goes deeper into appraisal, property-condition and transaction issues that can matter after you find the house.
Yes. USDA is different because eligibility isn’t just about the borrower.
The property must be located in an eligible area, and the household must meet USDA’s applicable income requirements.
For the USDA Single Family Housing Guaranteed Loan Program, the current upfront guarantee fee is 1.00% of the loan amount, and the current annual fee is 0.35%.
The upfront fee can be financed.
So a qualifying buyer can potentially purchase with no down payment while beginning with a loan balance slightly above the base amount because of the financed guarantee fee.
But before comparing USDA’s payment with the other three options, you have to answer a more basic question:
Is this particular house—and this particular household—eligible?
That makes USDA especially interesting around the outer portions of the St. Louis region, where a buyer shouldn’t assume eligibility or ineligibility based solely on whether an area “feels rural.”
USDA maintains the official eligibility tools. Property eligibility should be verified by address rather than guessed.
It can add hurdles. Government-backed loans have appraisal and property requirements that can raise questions on a house with safety, soundness or condition issues, so financing isn’t only a spreadsheet decision.
St. Louis has a lot of older housing.
A buyer may be comparing a century-old South City house, an older inner-ring suburban property, a newer subdivision home, or a property farther from the urban core.
Condition matters differently from one transaction to another.
Government-backed financing has appraisal and property requirements that can create additional questions when a property has certain safety, soundness or condition issues.
That does not mean an old house automatically fails FHA or VA financing.
And it does not mean Conventional financing has no property standards.
The practical lesson is simpler:
Choose the financing and the house together.
If you’re pursuing a property with obvious deferred maintenance, don’t wait until after you’re under contract to ask whether your financing creates another hurdle.
That is especially important when you’re competing against other buyers and don’t have much time between contract acceptance, inspections and appraisal.
Inspection: What Happens at a Home Inspection in St. Louis → → Appraisal: FHA Appraisal vs. Conventional Appraisal: What’s Different ↓ ↓ VA appraisal and property condition: What Happens When a VA Appraisal Fails in St. Louis → →Both determine market value, but an FHA appraiser must also check the property against HUD’s minimum property standards for safety, soundness and security. It’s the most important distinction for St. Louis buyers looking at older homes.
Both FHA and conventional appraisals determine market value. The difference is what else the appraiser must assess.
Note: Conventional appraisers may note condition issues in the report, but they rarely trigger repair requirements or stop the loan from closing.
Loan type affects how much protection you have against condition problems — but it doesn't eliminate the risk. Understanding cheap house regrets in St. Louis is important regardless of which loan path you take.
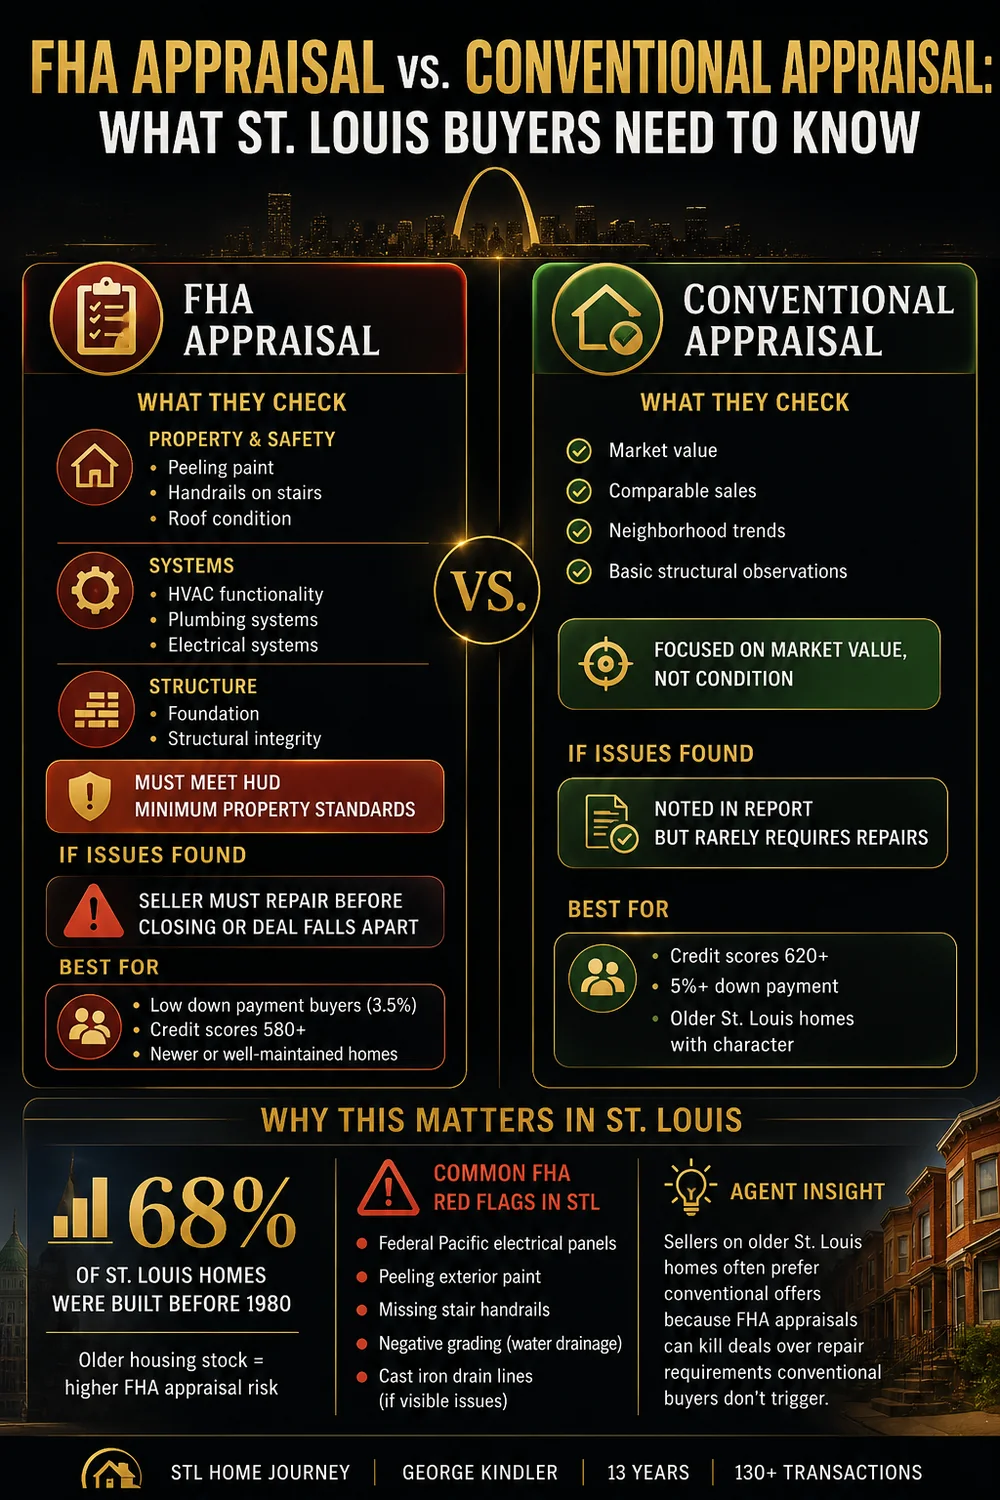
FHA appraisers follow HUD's Minimum Property Standards. If any of the following are found, they must be noted in the appraisal report and typically must be corrected before the loan can close:
Conventional appraisals focus on market value. The appraiser's job is to confirm the home is worth what the buyer is paying based on recent comparable sales in the area.
Conventional appraisers do observe the home's condition and note obvious issues in the report, but these observations rarely stop the loan from closing. The appraiser might note "deferred maintenance" or "functional obsolescence," but the lender typically does not require repairs unless the issue directly affects the property's structural integrity or marketability to a catastrophic degree.
This makes conventional loans significantly more flexible for older homes with cosmetic issues, deferred maintenance, or systems nearing the end of their useful life.
In my experience, conventional is often smoother on an older house with deferred maintenance, because an FHA appraisal can require repairs before closing that a conventional appraisal wouldn’t. That doesn’t rule FHA out; it means checking the house’s condition before you write the offer.
Safety and condition items: exposed wiring, peeling paint on homes built before 1978, missing handrails, grading that sends water toward the house, and systems that don’t work. Based on 13 years of transactions in the St. Louis market, these are the most common FHA appraisal issues that delay or kill deals:
Exposed electrical wiring or missing junction box covers are common in older St. Louis homes, especially in unfinished basements. FHA appraisals flag exposed wiring as a safety hazard and require it to be properly enclosed before closing. Cost: $300 to $1,500 depending on extent.
Peeling exterior paint on homes built before 1978 triggers FHA lead paint protocols. All peeling paint must be scraped, primed, and repainted by a lead-certified contractor. This can add $3,000 to $8,000 to the seller's cost -- or kill the deal if the seller refuses to address it.
Negative grading (ground sloping toward the foundation instead of away) is common on older St. Louis lots. FHA appraisers flag this as a drainage issue. Fixing it requires regrading, which can cost $2,000 to $6,000 depending on the severity.
Full breakdown of repair costs St. Louis buyers encounter during inspections and appraisals. St. Louis Home Repair Cost Guide → →Not automatically. A seller is choosing the offer they believe will close, and financing is one factor alongside price, buyer qualification, appraisal risk and the rest of the terms.
A seller isn’t really choosing a loan program. They’re choosing an offer and evaluating whether they believe that offer will close.
Financing can be part of that evaluation, but so can:
Sometimes a seller or listing agent may perceive Conventional financing as simpler.
That perception isn’t the same thing as saying FHA, VA or USDA financing is inherently weak.
A well-qualified buyer with a strong lender and financing that fits the property can still write a very strong offer.
The important question is whether the financing creates a problem for this house and this transaction, not whether someone has a blanket opinion about the letters on the preapproval.
On older homes with known condition issues, often yes, in my experience. Sellers there tend to prefer conventional offers because the appraisal is less likely to require repairs before closing.
In a multiple-offer situation where one buyer is FHA at $240,000 and another is conventional at $240,000, the conventional buyer has a significant advantage -- even though the price is identical. The seller knows the FHA appraisal carries repair risk that the conventional appraisal does not.
This does not mean FHA buyers cannot compete. It means your agent needs to acknowledge the appraisal risk in your offer and potentially offer a higher price, faster timeline, or stronger earnest money to compensate for that risk. (More on competing on terms in our guide to winning multiple offers without overpaying.)
No. FHA, conventional, VA and USDA are how the purchase is financed. MHDC, the primary down payment assistance program for St. Louis buyers, is a separate layer that works on top of them. This is where first-time buyers often get understandably confused.
FHA, Conventional, VA and USDA describe ways the underlying purchase can be financed.
Programs such as MHDC can involve another layer of eligibility and assistance.
So don’t start with:
Which first-time-buyer loan should I get?
Start with two questions:
Which underlying mortgage fits me and the property?
and then:
Is there an assistance program I qualify for that works with that financing?
Those questions are related, but they aren’t identical.
If keeping more of your savings is important, compare the financing first and then review my St. Louis first-time home buyer programs and assistance guide.
For Missouri buyers specifically considering MHDC, I also have a separate guide to MHDC First Place and Next Step so the detailed program rules don't have to be crammed into this mortgage comparison.
The one that fits your situation; there isn’t a universal winner.
You qualify for competitive Conventional terms, want to compare low-down-payment options, value the possibility of eventually removing PMI, or you’re purchasing a property where a government-backed loan could create additional transaction friction.
Its underwriting structure fits your financial profile and the combination of down payment, rate and mortgage insurance produces a better overall option than the Conventional alternatives available to you.
You’re eligible.
Don’t dismiss VA simply because another loan looks more familiar. Compare the funding fee, exemption status, interest rate, zero-down option and absence of monthly mortgage insurance before deciding.
Your household appears eligible and you’re considering a property that may fall within USDA-eligible geography.
Don’t assume a property qualifies because it’s outside St. Louis City—or fails because it looks suburban. Check the actual address.
Take the same house and change the financing.
What happens to:
That’s a much more useful comparison than simply asking whether FHA or Conventional is “better.”
The house may be identical.
The financing isn’t.
Calculator defaults (7.00% illustrative rate, property taxes of 1.12% of price, homeowners insurance of 1% of price, 0.60% estimated PMI) are illustrative assumptions used across STL Home Journey’s affordability tools, not market quotes. See the calculator methodology above for how each payment is estimated.
How your credit score affects your loan options, interest rate, and monthly payment in St. Louis. What Credit Score Do You Need to Buy a Home in St. Louis? → → See how mortgage insurance affects your true monthly cost across 79 St. Louis zip codes. St. Louis Affordability by Zip Code → →Know your number? Take it to the showing. My walk-through tool flags repairs room by room and totals the 2026 expected costs, so you can see whether a house still fits your budget once you add what it needs. Save or email your results to compare houses.
Costs and mortgage insurance
Four different payments, even at the same price and the same rate. A mortgage comparison gets confusing quickly because lenders quote different rates, buyers put different amounts down, taxes vary by property, and mortgage insurance depends on the borrower. Same House, Four Loans ↑
Because the price of the house is only one part of the payment. Why the Payment Changes ↑
Usually not. On many conventional loans you can ask to cancel private mortgage insurance once your balance is scheduled to reach 80% of the home’s original value, and it ends automatically at 78% if you’re current. And you don’t need 20% down to use conventional financing (how much down each loan needs). Conventional Loans and PMI ↑
Because of mortgage insurance: a 1.75% upfront premium added to the loan, plus an annual premium for as long as the rules require. FHA requires a minimum investment of 3.5% of the property’s adjusted value for the standard maximum-financing scenario. FHA and Mortgage Insurance ↑
Not by building equity. With less than 10% down, FHA’s annual premium lasts the life of the loan; with 10% or more down, it lasts 11 years. The usual way out early is refinancing into a conventional loan once you have 20% equity. Canceling FHA Mortgage Insurance ↑
Usually a one-time funding fee instead of monthly mortgage insurance. If you’re eligible for the VA home-loan benefit, VA deserves a real comparison, not a footnote underneath FHA and conventional. VA Loans ↑
Eligibility and credit
Yes. USDA is different because eligibility isn’t just about the borrower. USDA Loans ↑
It should weigh heavily, because your credit score matters more with conventional loans than FHA loans. For the minimum scores themselves, see what credit score you need. Credit Score: FHA or Conventional ↑
No. FHA, conventional, VA and USDA are how the purchase is financed. MHDC, the primary down payment assistance program for St. Louis buyers, is a separate layer that works on top of them. This is where first-time buyers often get understandably confused. Loans vs. Down Payment Assistance ↑
The one that fits your situation; there isn’t a universal winner. Which Loan to Look at First ↑
Older homes, appraisals and offers
It can add hurdles. Government-backed loans have appraisal and property requirements that can raise questions on a house with safety, soundness or condition issues, so financing isn’t only a spreadsheet decision. Older St. Louis Houses ↑
Both determine market value, but an FHA appraiser must also check the property against HUD’s minimum property standards for safety, soundness and security. It’s the most important distinction for St. Louis buyers looking at older homes. FHA vs. Conventional Appraisals ↑
In my experience, conventional is often smoother on an older house with deferred maintenance, because an FHA appraisal can require repairs before closing that a conventional appraisal wouldn’t. That doesn’t rule FHA out; it means checking the house’s condition before you write the offer. Older Homes in St. Louis ↑
Safety and condition items: exposed wiring, peeling paint on homes built before 1978, missing handrails, grading that sends water toward the house, and systems that don’t work. Based on 13 years of transactions in the St. Louis market, these are the most common FHA appraisal issues that delay or kill deals: Common FHA Appraisal Red Flags ↑
On older homes with known condition issues, often yes, in my experience. Sellers there tend to prefer conventional offers because the appraisal is less likely to require repairs before closing. How Sellers React to FHA Offers ↑
This is one piece of the St. Louis home buying process. See how it all fits together:
📚 Complete St. Louis Buyer Guide →
Grew up in South St. Louis, lived in Dogtown for 6 years, now in South County. You'll find us at Wellspring on Lindbergh on Sundays. I'm not selling you a house — I'm showing you how to think about buying or selling a house.